The Brexit pessimism sold down markets heavily. There is an old saying that cheap becomes cheaper.
While it is necessary to keep a positive frame of mind that markets will eventually recover, one should not forget the fact that a correction doesn't equates that all stocks are cheap now. The need to have some basic fundamental knowledge and control over one's emotion is applicable at these times.
By that I mean selling in panic, or buying in a frenzy.
I have been keen in quite a few companies lately, especially after they have gone into trouble. I guess it will help to discuss them briefly here
Noble
Clearly they are in debt and tons of trouble. But raising equity via such a heavy rights issue is a major deal-breaker for me. I guess what I can take away from reading Peter Lynch's One Up on Wall Street is that companies usually turnaround successfully from diluting shareholder's equity but the end-result usually wouldn't reward shareholders in the end.
There are better bets out there especially when your capital is as limited as mine.
Keppel Group
Keppel is a conglomerate and they want you to know that.. especially when their cashflow is severely affected by their Offshore and Marine (O&M) division. Revenues are contributed mostly by O&M and Property, and this is the first time in 3 years that property contributed more $ to Keppel than O&M.
Hence about 5,000 employees in O&M lost their jobs this year. Interesting enough, manpower cost remains the same for the last three years. I have no idea why this has come to pass and I hope shareholders asked during the AGM.
I have no idea how to value Keppel as it is a cyclical company. However I have faith that this company will definitely not go belly up as its major shareholder is Temasek Holdings. This does not mean that shareholders will lose capital (Remember NOL?).
Price of shares follows earnings in the long run. The question is whether Keppel is nicely priced at 5.2x? I have no idea. Its free cash flow is extremely volatile. But no worries about the dividend pay out and whether the company has shareholders' interest at heart. They paid 40 odd percent of retained earnings to sharehodlers in 2014, and paid 50% this year. I don't think dividends will suffer too much.
It is also vague in whether the 230million provisions for Sete Brasil's unsold rigs is enough. I have not scrutinized the report yet, though.
Yoma Strategic Holdings
I can't read annual reports off the screen, and I paid some printer almost 9 SGD for this report to be printed... but before I can finish half of the report, I am already put off by loans extended to customers. Hence I doubt I will be investing in this company. The introduction of his son as the CEO is no problem but it seems like an abrupt decision to me.
I intend to look elsewhere.
Monday, June 27, 2016

Wednesday, June 15, 2016
Time to Watch by the Sidelines?
This will be a really short post.
When I started investing, I frequently look at stocks trading at 52-weeks low. I have been doing it frequently from BarChart 52-weeks low, looking at its balance sheet and thinking if it makes a good turnaround bet. I had a few success in spotting these stocks but unfortunately, I wasn't confident in my abilities then, and watch stocks like Spartan Motors (SPAR), and MidSouth Bancorp go as high as 100%.
Such a practice can be pretty robotic, getting the list, and looking at its balance sheet quickly. It has been a while since I did that though, and I was very surprised today.
And today, there is really only a handful of stocks, regardless of market capitalization, that is trading at 52 weeks' low, and that smells like the market could possibly be overly optimistic.
I don't know about you, but I very much prefer to stand by the side of the court and wait.
While it is usually better to be vested most of the time, I think it might be prudent to lay hands off the American market. I still vested in SGX, in stocks that I find that are cheap.
Hopefully it will pay off in the long term.
Sunday, June 12, 2016
A Little Talk about My Portfolio
Primary Holdings
Sim Lian Group
Sim Lian Group is a respectable property developer that is purchased because I believe it is trading at a huge discount to its cashflow. The dividend yield is very high at the moment-- which is deceiving because the yield is derived from a special bonus last year.The biggest reason why this company is a little different from other small-scaled property developers-- check out the board members and you will know what I mean. I leave the fun to you..
Capitaland Commerical Trust
The stock is trading at a significant discount to its net asset value. Recently they have acquired the whole of CapitaGreen and is expecting it to be accretive for shareholders. This bring debt-to-equity at 37%, which is not all that bad.The property yield of CCT is actually weaker than Fraser Commerical Trust, but on the whole the quality of CCT's properties is higher, so I am not so concerned. Holding on to my paper losses at the moment and waiting for a good chance to average down.
Secondary Holdings
VICOM
A needless fear among investors for this stock, which is down-trending. The main rationale for buying this stock is for the quality of its dividends. When a friend of mine draw attention to me about it trading at 52-week low, I took up a small position without much consideration.Singapore Shipping Company
Small company, some debts, decent cashflow, but single-customer. Based on cashflow over the years, it is considered cheap at 0.27x and but there are some concerns with its business fundamentals, namely an inexperienced CEO (family business, ahem), and single-customer risk.DBS
DBS was purchased because it is trading at 0.9x book value. Not one of my proudest purchase since I did very little homework. It is a easy one to make since this is Singapore's biggest and one of Asia's biggest. I don't expect terrific gains.UOL
Trading at below book value and strong management. Even if Mr. Wee leaves the business, it will still go on strongly. However, the rental and property developing business is facing headwinds regionally, and earnings should remain suppressed. I have taken up a small position just in case the price becomes more favorable, and I can build on my position.Sing Holdings
With the latest quarter report, it appears that Sing Holdings is now debt-free, but have a variable asset in Account Receivables and unsold properties. It will be very interesting to see what it does for the rest of the year. Any company that is debt-free and a 0.5 book value per share should be quite safe for long term holding.Small Holdings
Ascendas Hospitality Trust
This stock is trading at below book value. It has a pretty patchy property yield as the trust is still so young (property accumulation stage), so the dividends should offset some risk. Staying vested and waiting on the side lines for a change in its story.CapitaMall Trust
This company's property yield is extremely impressive but it is trading at a significant price over book value. I will add on to my position should fear take over the market again, as it was with much regret that I did not partake in this during this Feb's great correction. I am eager to make this one of my main holdings.Sunday, June 5, 2016
One Up on Wall Street- A Short Review
I have just completed my first reading of Peter Lynch's classic text, "One Up on Wall Street," recently.
While the contents of this book is extremely palatable, it contains very little technical information and little is mentioned about valuation. I am a little amused because while this book is easily understandable, it should be best read by someone who had a look at more technical books such as "5 Rules to Successful Stock Investing."
The danger is that Mr Lynch made it sound too easy.
There are of course good takeaways from this book, such as classifying companies into 6 different categories, which are:
For e.g. assuming a stock like GSK, who is paying excellent dividends but isn't growing rapidly (a slow grower), started to fail in paying a dividend, that will be cause for concern.
An asset play that has its property valued down recently could also be cause for concern.
As with most books I think it is worthwhile to re-read them a couple of times to digest the concepts fully, and I am in the process of doing so.
Peter Lynch's One up on Wall Street in Book Depository
While the contents of this book is extremely palatable, it contains very little technical information and little is mentioned about valuation. I am a little amused because while this book is easily understandable, it should be best read by someone who had a look at more technical books such as "5 Rules to Successful Stock Investing."
The danger is that Mr Lynch made it sound too easy.
There are of course good takeaways from this book, such as classifying companies into 6 different categories, which are:
- Turnarounds- Stocks like Noble who are issuing new shares would be frown upon by Peter Lynch as they usually does not bode well for investors in the long run.
- Slow Growers- usually dividend stocks. Various REITs, ST Engineering comes to mind. This company desperately need a breakthrough of some sorts to increase revenues
- Fast Growers- Best World, who is expanding into China, have a sizable market to grow at.
- Stalwarts- Apple could be deem as a stalwart, but I thinking of DBS when it comes to local markets
- Cyclicals- Property Developers, Keppel, Sembcorp Marine. Times are bad now, but things will definitely be better if their balance sheet remains healthy. Basically cyclical companies generate tons of revenues during good times.
- Asset Plays- Stocks that are the proverbial "50cents for a dollar." Could be as simple as cash (Sing Holdings, possibly), property (SMRT with its many malls) , or companies holding equities of well-to-do equities (Yahoo comes in mind).
For e.g. assuming a stock like GSK, who is paying excellent dividends but isn't growing rapidly (a slow grower), started to fail in paying a dividend, that will be cause for concern.
An asset play that has its property valued down recently could also be cause for concern.
As with most books I think it is worthwhile to re-read them a couple of times to digest the concepts fully, and I am in the process of doing so.
Peter Lynch's One up on Wall Street in Book Depository
Wednesday, May 25, 2016
Beliefs to Hold Dear During a Bull Market
Business doesn't change from week to week.
When prices goes up, so does the risk.
When prices goes up, it doesn't necessarily reflect on the credibility of the company, nor the reliability of its earnings.
Good times will follow bad times; just like bad times will be succeed by good times. Nothing last forever.
Bulls do charge slower than a bear slide-- investors, like any human beings, prefer cash in the hand over unrealized profits (and certainly unrealized loss!!!).
Will the economy do well? Your guess is as bad as anyone's.
And finally, debts don't disappear during a bull market.
Invest wisely.
This too shall pass.
Monday, May 23, 2016
ISR Capital, A Ticking Timebomb?
In Oct 2013, three companies, Liongold, Blumont and Asiaons crash after a heavenly ascent of 800% within months, and crashed. Within 3 days, 8 billion worth of capital evaporated.
The MD of ISR Capital, Datuk Md Wira Dani Bin Abdul Daim, is the son of ex-Finance Minister of Malaysia, Tun Daim Zainuddin. He was also involved in Liongold, being its Executive Deputy Chairman. The CEO is Quah Su-Yin. Thanks to Google, you can find out if they are truly reputable or trustworthy.
So who are the major shareholders?
You can download their annual report from http://www.isrcap.com/attachment/201605041716311781353157_en.pdf or from SGX (which is the preferred choice).
 Both Datuk Jared Lim Chih Li and Mr Ng Teck Wah were involved in the penny stock crash of 2013, under Asiason Capital (which is renamed ISR Capital!)
http://business.asiaone.com/news/were-not-bunch-cowboys
Seems like a tightly knitted group if you ask me. All of the investment companies listed appears to be related to one another, with no reputable outsiders vested (or trusting) this company.
Assuming you are not interested in the history of a company's board members nor its senior management, have a look at the annual report.
Auditor's Statement
In short, the auditors' statement is the only portion written by the auditors.
The last 3 paragraphs are important-- it tells us that investigation is on-going, and there is an uncertainty involved with this company.
The Revenue
The company booked a revenue of almost 3 million compared to a paltry sum of 131,000 the year before. How could a company made such ridiculously high improvements within a year?The ROE and ROA were -500++% and -300++% the year before, and now we have 22.2% and 11.6%?
If we look under note 4, the company claims that it makes the entire revenue from consultancy, with only about 70,000SGD from interest income from debt securities. There are no further breakdown on revenue.
The company's segment information, on page 119, said that the company's main operation are split to
The Balance Sheet
This is the craziest part of this company
Let's look at current assets, which means assets that can be convert to cash within 1 year.
This company has only 20k of cash, and bulk of the assets (3million) comes from Trade Receivables. Which means sums that is owe to them by customers.
Note 13 (page 89) reveals
Note 14 shows you that in the past year, 30M was owe but 27M is already impaired. Erm...
The true entertainment comes from Non-Current Assets, Debt Securities, which contribute to 2.2M of the balance sheet. Under note 18, it says
The MD of ISR Capital, Datuk Md Wira Dani Bin Abdul Daim, is the son of ex-Finance Minister of Malaysia, Tun Daim Zainuddin. He was also involved in Liongold, being its Executive Deputy Chairman. The CEO is Quah Su-Yin. Thanks to Google, you can find out if they are truly reputable or trustworthy.
So who are the major shareholders?
You can download their annual report from http://www.isrcap.com/attachment/201605041716311781353157_en.pdf or from SGX (which is the preferred choice).

http://business.asiaone.com/news/were-not-bunch-cowboys
Seems like a tightly knitted group if you ask me. All of the investment companies listed appears to be related to one another, with no reputable outsiders vested (or trusting) this company.
Assuming you are not interested in the history of a company's board members nor its senior management, have a look at the annual report.
Auditor's Statement
Emphasis of matter
We draw your attention to Note 34 to the financial statements, which states that in April 2014, the Company with five of its wholly owned subsidiaries (one of which has since been disposed of), and two funds (including two subsidiaries of one of the funds) managed by the subsidiary of the Company that has since been disposed of, were served notices by the Commercial Affairs Department of the Singapore Police Force (“CAD”) for an investigation into an offence under the Securities and Futures Act, Chapter 289 (“SFA”). In the notices, the Company and those entities were asked to provide certain information pursuant to an investigation to be conducted by the CAD.
On 4 February 2015, the CAD confirmed to us that their investigation is still ongoing. As informed by the Board, apart from certain key personnel being requested to attend further interviews by the CAD in 2015, there have been no further new developments in the ongoing investigations.
In view of the above, there exist a material uncertainty, whether the ongoing investigation, the outcome of which is unknown, may have an impact on the Group’s ongoing business operations. Accordingly, the extent of adjustments, if any, that may arise from the ongoing investigations, may have an effect on the financial statements of the Group and the Company for the financial year ended 31 December 2015 and preceding years, if any.
Our opinion is not qualified in respect of this matter.The contents of an annual report are prepared by the company in question, not the auditor(s). The auditors' role is to audit the contents and give an opinion, as well as write the auditor statements produced on page 39 of the annual report.
In short, the auditors' statement is the only portion written by the auditors.
The last 3 paragraphs are important-- it tells us that investigation is on-going, and there is an uncertainty involved with this company.
The Revenue
The company booked a revenue of almost 3 million compared to a paltry sum of 131,000 the year before. How could a company made such ridiculously high improvements within a year?The ROE and ROA were -500++% and -300++% the year before, and now we have 22.2% and 11.6%?
If we look under note 4, the company claims that it makes the entire revenue from consultancy, with only about 70,000SGD from interest income from debt securities. There are no further breakdown on revenue.
The company's segment information, on page 119, said that the company's main operation are split to
- consultancy (IPOs?)
- investment management (no revenues recorded this year!?)
The Balance Sheet
This is the craziest part of this company
Let's look at current assets, which means assets that can be convert to cash within 1 year.
This company has only 20k of cash, and bulk of the assets (3million) comes from Trade Receivables. Which means sums that is owe to them by customers.
Note 13 (page 89) reveals
- about 3.171M of receivables
- After impairment (which means probably, not going to get these sums), it stands at 2.8M
- Amount already due by less than 90 days, the full sum of 2.8
- Page 90 says
These receivables are not secured by any collateral or credit enhancements.
Which means, this company is screwed if those "customers" don't pay!
Note 14 shows you that in the past year, 30M was owe but 27M is already impaired. Erm...
The true entertainment comes from Non-Current Assets, Debt Securities, which contribute to 2.2M of the balance sheet. Under note 18, it says
A debt facility with a principal amount of S$2,350,000 has been extended to a third party in 2015 for a period of five years. Interest is charged at 12% per annum with a 5% arrangement fee deducted upfront at each disbursement. The effective interest rate is computed at 13.4%.
What kind of rubbish credit rating is this 3rd party that will necessitate it taking a loan of 12% per annum? And the next paragraph says:
The debt facility could be drawn down by the third party for up to S$5,000,000 with maturity due 2020. The undrawn balance as at 31 December 2015 was S$2,650,000
It is telling you: This 3rd part can borrow from us another 2.65M.
This is exciting because I don't think ISR has that capital.
What can probably happen is that this mysterious 3rd party can keep borrowing from ISR Capital, as long as ISR keep issuing new shares, and then ISR can write off these "bad" debts?
And it is already happening. Look at Note 22
CONVERTIBLE REDEEMABLE BONDS
The proposed issuance of 2% convertible redeemable bonds due 2018 (the “Bonds”) with an aggregate principal amount of up to S$35,000,000 comprising seven tranches of bonds was approved by shareholders at an Extraordinary General
Meeting held on 8 September 2015. Each tranche comprises five equal sub-tranches of S$1,000,000 each. S$3,000,000 of the Tranche 1 Bonds were issued in September and October 2015. As at 31 December 2015, Bonds with a face value of S$750,000 have been converted into 187,500,000 ordinary shares. The present value of the Bonds after conversion amounted to S$2,053,672, which was arrived at using 5.5% per annum, an average rate compiled from interest rate quotations of 10 leading banks and financial institutions. The Bonds that remained outstanding as at 31 December 2015 were subjected to an interest rate of 2% per annum, payable in arrears on 31 December in 2015. Please refer to Note 20 for bond interest payable as at 31 December 2015.
As at 31 December 2015, the Company allocated approximately S$2,200,000 for investments in debt securities and approximately S$480,000 for general working capital (such as payment of remuneration of directors and employees, office rentals, insurance premiums and professional fees).
Stay away from this company.
As of writing, this stock has gain another 10% or so in a single day. Just because the price goes up, doesn't mean that the company is doing well. For those speculating, do question yourself on the ethical aspects.
As of writing, this stock has gain another 10% or so in a single day. Just because the price goes up, doesn't mean that the company is doing well. For those speculating, do question yourself on the ethical aspects.
Friday, May 20, 2016
Investment Rudder
A rudder is a vertical piece of wood that steers the boat. Small, and largely concealed by water, you will largely go nowhere without it. You don't usually see it, and neither do you hear investors talking about it.
Is it important to have an investment principle?
Graham, Schloss, and Buffett (in the early years) largely lived by the same principles, which is to look for $1 companies priced at 60 cents. The big difference in the early years is that Buffett is so sure of his analysis, that he is willing to dump a large part of his net worth into a single stock.
I think it is necessary to be stubborn as a value investor. When Schloss passed Graham a nice little company to Graham, the latter replied that it isn't the type of company that he is interested in. That nice little company was call Xerox, and they could have term it a growth stock then. Graham remain successful and beat the market by 2 percent or so for 20 over years.
***
Of all investors, I aligned myself to Walter Schloss's principles the most.
I am not great at evaluating a business (this is something I need to add to my toolbox), hence, sticking to the balance sheet can be a smart move.
Two of the companies that I missed out during the correction this year were Spartan Motors (NYSE:SPAR) and Midsouth Bancorp (NYSE:MSL). Both got on my radar during their dips, and both have a good balance sheet. Spartan Motors however did not have great earnings.
Both companies went up by almost 80% as of this writing, despite being small companies.
The idea is that earnings are unpredictable, but balance sheet is. I don't find companies that are heavily leveraged, attractive. Unless it is a failing business with many years of negative cashflow, companies usually trade above their book value.
While both Schloss and Buffett do not disclose their holdings (during the early years), each have their own reasons for doing so. Buffett did not want anyone to ride on his coattails, while Schloss has a bunch of companies which many will be afraid to invest in.
For instance, someone like Schloss might be interested in Noble (SGX:N21), but he will diversify his risk.
***
I live frugally and have no great lust for the luxuries of life. I do find myself an odd-ball for not knowing the movements of watches, no desire for a nice car, salivate the thoughts of dining at the best restaurants.
One day, I might just become a full time investor, living in a small room in Vietnam (to keep costs down, and I love the food there). There will be
- A shelf with all the books to keep my investment rudder intact.
- Another shelf with all the annual reports of companies I am keen of.
- A little printer to print these annual reports.
- A bean bag to sit on while reading the reports.
- A small notebook and a fairly large U shaped desk (made of wood of course)
- A modest steel chair.
- A large erasable whiteboard
- A tatami mattress to sleep on
- A space for my cat to live in.
Monday, May 16, 2016
The Best Long-term Investment
I made the plunge recently and invest on a course, conducted by Mr SS Sandhu. The course is Analyzing Financial Statements and is hosted by SGX Academy.
First off, the changes it made to my attitude to investing.
It might changes my approach to investing. My main strategy in investing is looking for $1 companies that cost 60cents. Hence, my first step is to look at companies that have recorded a significant drop. However, perhaps this time round, I should be reading the news a little more proactively, as they might spell an improvement to a company that has not suffered a discount.
I have taken a significant interest in the board and senior management. I used to look at management as something generic, but now I realize they could bring certain value to the company:
- They could have ties to important government/ financial institutions
- They can have (or not have!) experience that is useful.
- Their background can suggest if they have the competence for the job.
I adopted a deeper appreciation to the balance sheet, the quality of its assets, and the details of its liabilities. Not all assets are equal; every liability deserves a closer look. Hidden assets (and liabilities!) are actually recorded in the annual report.
One can understand the business better just from reading the annual report. For instance, I understand now how low margin a property development company is, and most of them should at least have another branch of income available.
I highly recommend this course for the instructor is extremely experienced and intrinsically passionate in teaching his self-developed materials. However you will need to have a rudimentary understanding of the financial statements in the first place, in order to fully adsorb majority of the materials. Annual reports are a toughie-- it will pay for you to study some AR before going for this course.
Thursday, April 28, 2016
Why WDC was Cheap at 40.x
From time to time, the market offers you a company with discounts.
Some of it is opportunity and some of it isn't. I feel that the following is worthy to think about
(a) if the sell-down is due to rational reasons that will hurt earnings. Prices follow earnings in the short term
(b) if the company is already a decent company without the crisis. Disregarding the price, is the company doing well?
-are share holder equity increasing?
-is return of invested capital increasing?
-is debt larger than equity? You might make a mistake, or the market might become inefficient for a long time.
-is dividend history steady?
(c) perform valuation and see if the discount is worth it.
Do note that WDC has a high beta of 1.6 (which means it moves up or down 1.6 times the rate of the market as a whole).
However, it doesn't matter what type of companies it is, or if the beta is high/low. What matters is if they are cheap and performing fine as a business.

This represent a support (which is the price-level where stocks seems to _not_ fall under) level at roughly 40-ish. This support is tested in mid Feb 2016, during which the markets rally together as a whole. Hence, it would be irreliable to mark this as a credible support given that it is untested.
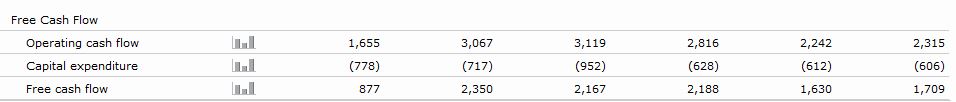 As you can see, cashflow isn't spectacular, but decent.
Next, we look at how the company is performing under key ratios
I looked at the revenues and it has pretty good years till 2015. But the key thing is to look at gross and operating margins, since revenues can be propped by acquiring companies. I noted that gross and operating margins are very healthy, increasing even.
From the same page, I can see the Cost of Goods and Services (COGS) is going down. Assets turnover and return of assets is going down. Return of equity is going down, but still respectable at 12%. This means we should pay attention to it from quarter to quarter.
Interest coverage represents how well the company is repaying its loans. Company servicing its loans pretty well at 25.34.
Moving on to Income Statements, I tend to look at percentages instead of actual figures as it make sense. There is a "%" button to click on within Morningstar.

I can see that cost of revenue is kept well control, and gross profits are high. Company devotes money on R&D steadily. Again, note the low interest expense.
Next Balance Sheet
 What I saw is about 30% of current assets in cash, but what pleases me is the ability of this company to get payments. Receivables is reducing since 2011.
Inventory does not hold a great percentage of this company's balance sheet. You can take the the inventory figure, in exact cash figures, and compute it as a figure of revenues. This is known as asset turnover and represent the number of times a company turn over its assets. A increasing figure means efficiency.
Moving down to liabilities,

We can see that liabilities begin to lower... long term and short term (payable < 1 year) debt is kept low at less than 20%
Finally, when you subtract assets with liabilities, you get equity.


Equity fell from an incredible 2011 of 67.6% of the balance sheet to 53.98%. However, it has been increasing since. Lovely.
And finally, dividends history offers a clue if the company has shareholders' interests at heart.

Now that we are pretty happy with the company, it is time to check if the price is good.
Immediately I start to do my cashflow valuation on this stock and for a very modest rate of 3% growth, off a reduced free cashflow of 1.6 billion, and a 12 percent discount rate, I get a figure of about 40.4 dollars. I bought the stock at 40.75 on the 15-April and went to bed. Unfortunately I do miss out on the lowest price of 40.18, but you can never time the market.. this deal is almost a no brainer. Note again that I reduce free cash flow by 100 million dollars.
It doesn't matter if it is a technology or a brick-and-mortar business. WDC is a fairly decent company with a very decent discounts. It has pretty low debts as a company. However, WDC isn't a company with any sort of moat and needs to be monitored carefully.
Update: WDC announced lesser than expected earnings per share of 1.21 to the expected 1.28, with less revenue compared to the same quarter last year. The price fell by some 4 percent on after-market sales. I have liquidated my position at 47.2 earlier after noticing a huge resistance intra-day..
Some of it is opportunity and some of it isn't. I feel that the following is worthy to think about
(a) if the sell-down is due to rational reasons that will hurt earnings. Prices follow earnings in the short term
(b) if the company is already a decent company without the crisis. Disregarding the price, is the company doing well?
-are share holder equity increasing?
-is return of invested capital increasing?
-is debt larger than equity? You might make a mistake, or the market might become inefficient for a long time.
-is dividend history steady?
(c) perform valuation and see if the discount is worth it.
Do note that WDC has a high beta of 1.6 (which means it moves up or down 1.6 times the rate of the market as a whole).
However, it doesn't matter what type of companies it is, or if the beta is high/low. What matters is if they are cheap and performing fine as a business.
The Selldown
Due to a large sell down by Seagate of 25% on 13-April-2016, investors panic and sold down WDC by 6.6%, and a further 3.2% the next day. The reasons given by Seagate's management was difficult PC market
Market usually affects sector movements, and the entire sector usually moves in tandem. Hence a price movement like this is not unusual, given that WDC and Seagate are #1 and #2 in the market. I first read this from Jesse Livermore's Tandem Trading ideas.
This represent a support (which is the price-level where stocks seems to _not_ fall under) level at roughly 40-ish. This support is tested in mid Feb 2016, during which the markets rally together as a whole. Hence, it would be irreliable to mark this as a credible support given that it is untested.
Looking at its Financial Statements
So how is WDC performing as a company? Let's take a quick look at Morningstar figures, which cost nothing to view. The first thing you want to look at is cashflowNext, we look at how the company is performing under key ratios
I looked at the revenues and it has pretty good years till 2015. But the key thing is to look at gross and operating margins, since revenues can be propped by acquiring companies. I noted that gross and operating margins are very healthy, increasing even.
From the same page, I can see the Cost of Goods and Services (COGS) is going down. Assets turnover and return of assets is going down. Return of equity is going down, but still respectable at 12%. This means we should pay attention to it from quarter to quarter.
Interest coverage represents how well the company is repaying its loans. Company servicing its loans pretty well at 25.34.
Moving on to Income Statements, I tend to look at percentages instead of actual figures as it make sense. There is a "%" button to click on within Morningstar.
I can see that cost of revenue is kept well control, and gross profits are high. Company devotes money on R&D steadily. Again, note the low interest expense.
Next Balance Sheet
Increasing receivables could present the company booking unpaid money as revenue. Be careful.
Inventory does not hold a great percentage of this company's balance sheet. You can take the the inventory figure, in exact cash figures, and compute it as a figure of revenues. This is known as asset turnover and represent the number of times a company turn over its assets. A increasing figure means efficiency.
Moving down to liabilities,
We can see that liabilities begin to lower... long term and short term (payable < 1 year) debt is kept low at less than 20%
Finally, when you subtract assets with liabilities, you get equity.
Equity fell from an incredible 2011 of 67.6% of the balance sheet to 53.98%. However, it has been increasing since. Lovely.
And finally, dividends history offers a clue if the company has shareholders' interests at heart.
Now that we are pretty happy with the company, it is time to check if the price is good.
Immediately I start to do my cashflow valuation on this stock and for a very modest rate of 3% growth, off a reduced free cashflow of 1.6 billion, and a 12 percent discount rate, I get a figure of about 40.4 dollars. I bought the stock at 40.75 on the 15-April and went to bed. Unfortunately I do miss out on the lowest price of 40.18, but you can never time the market.. this deal is almost a no brainer. Note again that I reduce free cash flow by 100 million dollars.
It doesn't matter if it is a technology or a brick-and-mortar business. WDC is a fairly decent company with a very decent discounts. It has pretty low debts as a company. However, WDC isn't a company with any sort of moat and needs to be monitored carefully.
Update: WDC announced lesser than expected earnings per share of 1.21 to the expected 1.28, with less revenue compared to the same quarter last year. The price fell by some 4 percent on after-market sales. I have liquidated my position at 47.2 earlier after noticing a huge resistance intra-day..
Tuesday, April 26, 2016
Cheap, Riskless Blue-chips.
You have definitely heard this line somewhere:
This is one of the most dangerous belief to adopt.
Whether one should inject capital into a company depend largely on two main factors:
There are good companies with bad prices. There are drowning companies with great-looking, seductive prices. Both can be equally dangerous, although I think if you have the tenacity, usually you won't make huge losses with the former, unless you are terribly ignorant.
For instance, let's take a look at a company like Helwett Packard Incorporated (NYSE:HPQ). You definitely have seen a HP printer somewhere, or used their laptops even. To be honest, I like their products. I am even holding a small amount of its stock.
I hope you recall that this blog is about sharing my mistakes!
One of the metrics used by investors is the Price-to-Book ratio. It basically means looking into the balance sheet, and taking the value of total assets minus total liabilities. What you get is call net asset, or equity.
Divide that value with the number of shares, and you get a figure known as book value per share. The ratio between the price and book value per share is known as P/B ratio. If it is lesser than one, it is generally considered cheap.
It basically means you paying less than 1 dollar for 1 dollar of assets.
Companies often report earnings every quarter, and a figure call Earnings Per Share, popularly abbreviated as eps. The ratio between price and eps is known as Price to Earnings, also popularly known as P/E ratio.
Somewhere in November 2015, HP split into two companies, HPQ (printers, desktops and laptops) and HPE (deals with cloud computer and server stuff). HPQ reported earnings and it was bad. The market pull the price down from 14.x to 12.x
The book value per share, ladies and gentlemen, is 15.75 then. This brings P/B to 0.8.
The P/E ratio, was less than 6. You will find this to be an attractive value. Generally, most people will consider a P/E of less than 20, cheap.
And so I went in. On the benefit of hindsight and new knowledge, I regretted.
During the great correction between late Decemeber 2015 and Feb 2016, HPQ dropped to almost the low 9 dollars. If you have done cashflow valuation (I will share this in a latter post), 9 bucks is a very very safe price.
That was Feb 2016 then. We are now in late April 2016, with the Dow at almost 18000 today, HPQ is still only around my buy price, and I am suffering a loss due to a less favorable currency rate.
There were two mistakes that I learnt from this trade.
(a) HPQ was carrying a lot of goodwill in its balance sheet.
(b) P/E and P/B are not great indicators of cheap companies.
Earnings can be largely doctored, and we are usually looking at last twelve months of earnings. What about future earnings? If it plunges, the P/E goes right up.
P/B ... well... rich asset does not translate into money-making, generally. Investors who largely invest in this kind of stock will hold a large basket of stock. This is not a wrong strategy. But you need to be an expert of the balance sheet.
Some assets such as
ALL of the above have subjective value.
Summary: it is what you think that you know, but just aint so, that kills you.
When the price goes up, you make money and nobody asks any questions. It is when you are losing money that doubts creeps in and kills you.
There are a lot of companies listed in indexes that are no doubt good companies but usually they are over-valued. P/E and P/B are useful, but cashflow valuation is still king.
Invest in blue chips. They are less risky.
This is one of the most dangerous belief to adopt.
Whether one should inject capital into a company depend largely on two main factors:
- Is it good?
- Right price?
There are good companies with bad prices. There are drowning companies with great-looking, seductive prices. Both can be equally dangerous, although I think if you have the tenacity, usually you won't make huge losses with the former, unless you are terribly ignorant.
For instance, let's take a look at a company like Helwett Packard Incorporated (NYSE:HPQ). You definitely have seen a HP printer somewhere, or used their laptops even. To be honest, I like their products. I am even holding a small amount of its stock.
I hope you recall that this blog is about sharing my mistakes!
One of the metrics used by investors is the Price-to-Book ratio. It basically means looking into the balance sheet, and taking the value of total assets minus total liabilities. What you get is call net asset, or equity.
Divide that value with the number of shares, and you get a figure known as book value per share. The ratio between the price and book value per share is known as P/B ratio. If it is lesser than one, it is generally considered cheap.
It basically means you paying less than 1 dollar for 1 dollar of assets.
Companies often report earnings every quarter, and a figure call Earnings Per Share, popularly abbreviated as eps. The ratio between price and eps is known as Price to Earnings, also popularly known as P/E ratio.
Somewhere in November 2015, HP split into two companies, HPQ (printers, desktops and laptops) and HPE (deals with cloud computer and server stuff). HPQ reported earnings and it was bad. The market pull the price down from 14.x to 12.x
The book value per share, ladies and gentlemen, is 15.75 then. This brings P/B to 0.8.
The P/E ratio, was less than 6. You will find this to be an attractive value. Generally, most people will consider a P/E of less than 20, cheap.
And so I went in. On the benefit of hindsight and new knowledge, I regretted.
During the great correction between late Decemeber 2015 and Feb 2016, HPQ dropped to almost the low 9 dollars. If you have done cashflow valuation (I will share this in a latter post), 9 bucks is a very very safe price.
That was Feb 2016 then. We are now in late April 2016, with the Dow at almost 18000 today, HPQ is still only around my buy price, and I am suffering a loss due to a less favorable currency rate.
There were two mistakes that I learnt from this trade.
(a) HPQ was carrying a lot of goodwill in its balance sheet.
(b) P/E and P/B are not great indicators of cheap companies.
Earnings can be largely doctored, and we are usually looking at last twelve months of earnings. What about future earnings? If it plunges, the P/E goes right up.
P/B ... well... rich asset does not translate into money-making, generally. Investors who largely invest in this kind of stock will hold a large basket of stock. This is not a wrong strategy. But you need to be an expert of the balance sheet.
Some assets such as
- goodwill (excessive amount paid when companies are acquired are considered assets and stored here)
- intangibles
- accounts receivable (amount of money customers still owe the company)
- inventory (stuff that are sold to customers)
- plants, properties and equipment (assets that are used to create the products or services)
ALL of the above have subjective value.
- HPQ acquired Compaq in the past and paid too dearly for it. That bulk ends up in goodwill.
- It is tough to value intangibles.
- You depending on the good faith of those debtors to pay up in Accounts Receivable
- Inventory can go seriously out of fashion. Items such as a dental floss will probably de-value slower than the latest iPad. You have to judge...
- Plants, properties.... well.... good luck selling them when the company liquidates..
Summary: it is what you think that you know, but just aint so, that kills you.
When the price goes up, you make money and nobody asks any questions. It is when you are losing money that doubts creeps in and kills you.
There are a lot of companies listed in indexes that are no doubt good companies but usually they are over-valued. P/E and P/B are useful, but cashflow valuation is still king.
Sunday, April 24, 2016
Introduction
There are no safe investments in this world.
Investing in stocks is a risky operation for the uneducated. It takes more than simple common sense and can be emotionally draining.
My first attempt in investing was done based on chart reading, and like every first investment, it was deceptively easy. To quote Bill Gates, you usually don't learn much from successes. Easy successes in the stock market are usually pre-cursors to large, daunting failures.
This is a game which you are going to make lots of mistakes. But yet it is a game that most small to median income earners are forced to play (I can't speak for high net-worth individuals). After my early failed attempts at trading, I have adopted value investing as it suits my temperament and lifestyle.
There are successful traders out there, but mathematically they will probably methodically cut losses in 7/10 trades and win 3 in order to be profitable. It also must involve leverage (borrowings) in order to make sense in trading. If you are looking to earn 3-5K USD with trading, it is possible. It takes a lot of heart to trade, and an apprenticeship is necessary. I possess neither.
It is very fair, you need huge money to earn money, be it investing or trading. And within each field, only the best earn spectacular returns. Life is unfair in many ways but this is the exception.
I have many, and I expect more along the way. These failures rewarded me with lessons that hopefully will serve me well in the future.
This blog shall serve as a collection of the lessons that the stock market offered to me, as well as my thoughts.
Subscribe to:
Posts (Atom)
-
 Portfolio Returns: 99.3% STI: 29.2% Tracker: 25.6% S&P 500: 13.35% I believe returns should be correct this time round since Evan of Sto...
-
You have definitely heard this line somewhere: Invest in blue chips. They are less risky. This is one of the most dangerous belief to ad...